Broadcom's AI Revenue Opportunity Is Bigger Than Its Stock Price Suggests
Published by AINave Editorial • Reviewed by Ramit
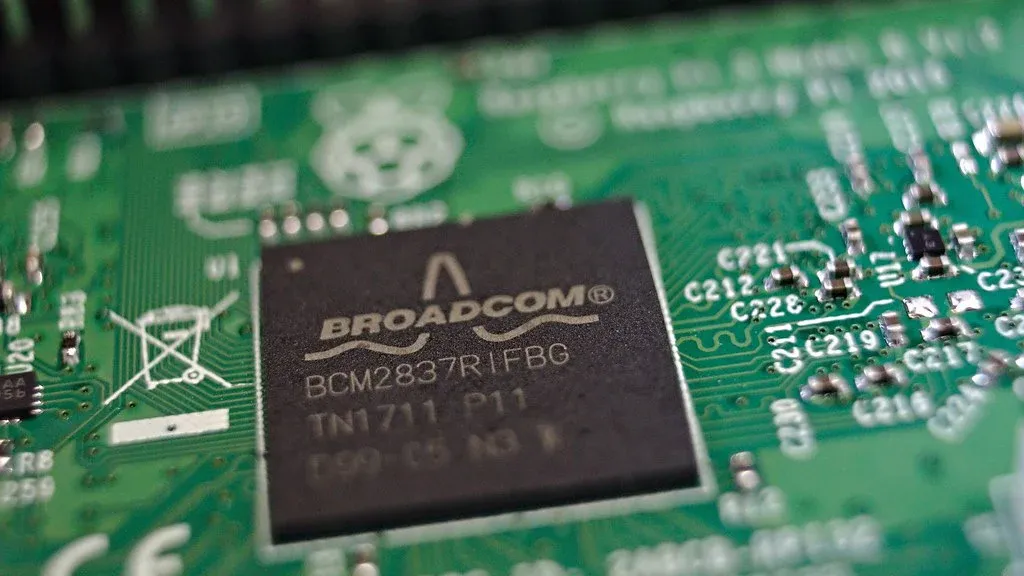
Broadcom just posted its ninth straight earnings beat with AI semiconductor revenue exploding to $16.70 billion in fiscal Q3 2026, up 221% from a year earlier, yet the stock has barely moved in 2026. For AI builders, this disconnect matters because Broadcom's custom silicon and networking components are powering the largest hyperscaler AI deployments outside of NVIDIA, and the company's ability to convert that demand into sustained revenue gains has direct implications for infrastructure supply and pricing.
The numbers that tell two different stories
Broadcom's fiscal Q3 2026 revenue hit $29.59 billion, up 85.5% year over year, with AI semiconductor making up more than half of that total at $16.70 billion. Management guided Q4 AI revenue to $21.7 billion, a 236% year-over-year increase. CEO Hock Tan has publicly targeted exceeding $100 billion in AI sales by 2027, a number that would require the current quarterly run rate to more than double in roughly a year.
The bull case rests on concrete hyperscaler commitments. On the Q2 fiscal 2026 earnings call, Tan disclosed Meta's plan to deploy 3 gigawatts through 2028, an OpenAI commitment of 1.3 gigawatts in 2027 as part of a broader 10 gigawatts by 2029 agreement, and $6 billion in additional purchase orders from two unnamed hyperscalers.
Why the market isn't buying the story yet
Despite the revenue explosion, Broadcom's stock has drifted sideways, up just 3.71% year-to-date. The disconnect comes from two sources. First, customer concentration is a primary risk. Broadcom's AI business depends on a limited set of hyperscale customers -- any capital expenditure pullback from Google, Meta, or OpenAI would flow directly through to revenue. Second, gross margins are expected to compress toward 74% as AI silicon becomes a larger mix. CFO Kirsten Spears countered that semiconductor margins remain structurally stable, but the trend bears watching.
Valuation reflects this skepticism. Broadcom trades at a forward P/E around 19, a discount to NVIDIA's forward P/E near 24. Marvell, the closest custom-silicon competitor, trades even higher on a growth-adjusted basis, but Broadcom's size gives it scale advantages in manufacturing and customer relationships.
What AI builders should watch
For teams building AI infrastructure or deploying at scale, Broadcom's trajectory signals several trends. First, gigawatt-scale deployments are becoming the normal unit of planning. Meta and OpenAI are not committing to these numbers unless they expect sustained demand for inference and training. Second, custom silicon (ASICs) is absorbing a growing share of hyperscaler spend, which means merchant GPU availability may loosen over time as large customers build their own accelerators. Third, Broadcom's networking chips are equally critical -- Tan described demand for XPUs and networking as "insatiable," which should matter for anyone planning data center buildouts.
Caveats to keep in mind
All forward-looking targets are management statements, not independently verified projections. The $100 billion AI revenue target by 2027 depends on continued hyperscaler spending and successful execution of the custom-silicon roadmap. A broad capex pause, or even a slowdown in deployment schedules at Meta or OpenAI, would directly challenge the bull case. Additionally, Broadcom's reported $60 billion in off-balance-sheet debt financing for AI chip projects adds financial complexity that could amplify downside in a downturn.
The practical takeaway for AI builders: Broadcom's revenue trajectory confirms that the demand for AI compute is not slowing, but the market's skepticism around concentration and margin compression is a healthy reminder that infrastructure buildouts carry their own risks. Whether you are buying chips or building on top of them, the next 12 to 18 months of hyperscaler capex will determine whether Broadcom's stock eventually follows its revenue or remains stuck in the gap.
FAQs
Sources
- Broadcom’s AI Opportunity Is Bigger Than Its Stock Price Suggests
- AVGO Stock: What Broadcom's AI Outlook Miss Really Means
- Broadcom’s $200 Billion AI Opportunity Is Drawing New... - AOL
- Broadcom's AI Momentum: Is the Stock's Post-Earnings Dip a Buying...
- Broadcom AI Revenue Outlook Suggests Upside... | Investing.com
- Broadcom's AI chip revenue grew 221% last quarter. A $1,000 investment a year ago would be worth this much today.
- The market hasn't been giving Oracle and Broadcom enough credit for their solid growth and prospects
- Broadcom Q3: Hardware Could Be The Missing Piece In An AI Portfolio
- Broadcom’s (AVGO) Massive New Debt Deal Points To Where AI Is Headed
- Broadcom Q2 Earnings Call Spotlights AI Demand Surge
- Broadcom’s Real Constraint Isn’t Demand. It’s Supply. - Insider Monkey
- Broadcom's AI Growth and Margin Pressure: Is the Sell-Off a Buying...
- Broadcom earnings deep dive: AI growth vs. Market expectations...
- Broadcom's AI Boom Carries a Hidden Price Tag That Has Credit Markets on Edge
- Marvell vs. Broadcom: One AI Stock Looks More Attractive Right Now